In this article
The Central Bank of Nigeria (CBN) has cut its benchmark interest rate from 26.5 per cent to 23 per cent, delivering one of the biggest reductions in its recent monetary policy cycle and signalling a shift towards supporting economic activity as inflation continues to moderate.
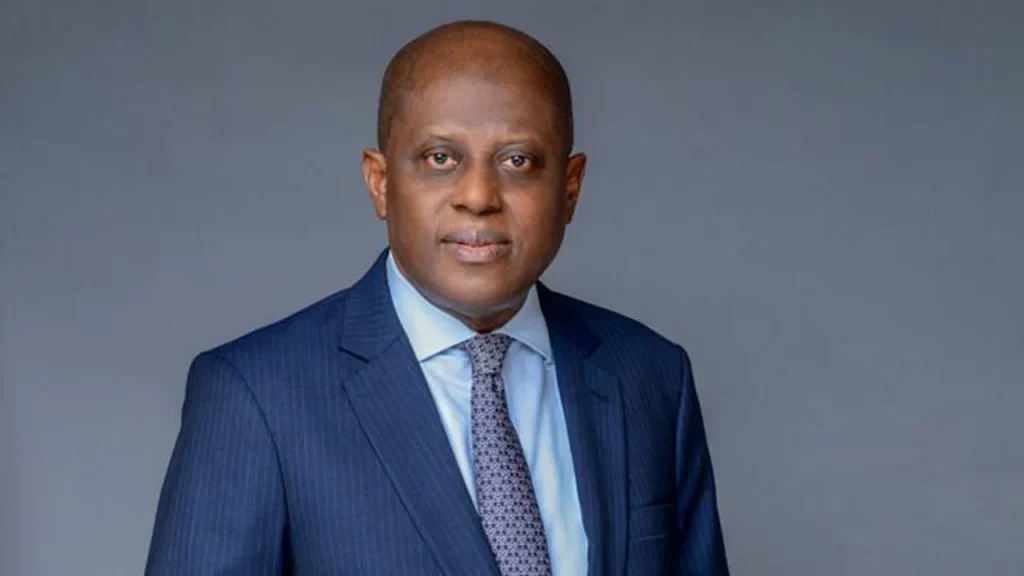
The decision was announced by CBN Governor Olayemi Cardoso on Tuesday following the 307th meeting of the Monetary Policy Committee (MPC) in Abuja.
The 350-basis-point reduction takes the Monetary Policy Rate (MPR) to 23 per cent. The MPC also recalibrated the Standing Facilities Corridor to +50/-300 basis points around the MPR, while maintaining existing Cash Reserve Requirement levels for banks.
For ordinary Nigerians, however, the immediate question is not simply what the MPR is.
It is:
Will bank loans become cheaper? Will savings interest rates fall? What happens to investments? And when will Nigerians actually feel the impact?
Here is what the CBN’s decision could mean.
What is the CBN’s new interest rate?
The CBN’s Monetary Policy Rate (MPR) is the benchmark rate used by the central bank to influence borrowing costs and other interest rates across the financial system.
The MPC has now reduced the MPR from 26.5 per cent to 23 per cent, a cut of 3.5 percentage points.
The decision follows the CBN’s earlier 50-basis-point reduction in February, after which the MPC kept the MPR at 26.5 per cent at subsequent meetings.
The latest decision therefore represents a significant change in the direction of monetary policy.
Why did the CBN cut the interest rate?
One of the major factors behind the decision is the moderation in inflation.
Nigeria’s headline inflation fell to 15.39 per cent in August 2026, from 15.43 per cent in July, according to the National Bureau of Statistics. Month-on-month inflation also slowed to 0.71 per cent from 1.57 per cent in July.
Food inflation also eased to 19.57 per cent year-on-year in August.
The easing in inflation, alongside relative foreign-exchange stability and improving economic conditions, has created more room for the CBN to loosen monetary conditions.
The decision also comes after months of relatively tight monetary policy aimed at containing inflation and supporting macroeconomic stability.
What does the 23% interest rate mean for Nigerians?
The effect will not be identical for everyone.
Borrowers, savers, investors and businesses could experience different consequences.
1. Will bank loan rates become cheaper?
They could, but not immediately and not necessarily by 3.5 percentage points.
The MPR is a benchmark; it does not mean every Nigerian bank must automatically reduce its lending rate by 3.5 percentage points.
Banks consider several factors when pricing loans, including their funding costs, liquidity, credit risk, operating costs and the risk profile of individual borrowers.
However, a lower policy rate can reduce the overall cost of funds in the financial system over time.
If banks transmit the reduction to customers, businesses and households could eventually see lower borrowing costs.
This could benefit:
- Small and medium-sized businesses
- Manufacturers
- Traders
- Farmers
- Mortgage borrowers
- Consumers using bank credit
- Companies seeking expansion finance
But borrowers should not expect an automatic reduction in loan rates immediately after the MPC announcement.
2. What happens to savings interest rates?
This is where the rate cut could produce a different outcome.
When market interest rates decline, banks may eventually reduce the rates they offer on some savings and deposit products.
That means Nigerians who depend heavily on interest income from bank deposits could see lower returns if banks adjust their deposit rates downward.
However, the timing and size of any reduction will depend on individual banks and market conditions.
A 23 per cent MPR does not mean your savings account will suddenly pay 23 per cent — or fall by 3.5 percentage points.
Banks price deposits according to their own funding needs and competitive conditions.
3. What happens to fixed-income investments?
The rate cut could also affect the returns available on fixed-income instruments such as:
- Treasury bills
- Government bonds
- Money-market investments
- Other interest-bearing securities
When expectations of lower interest rates become established, yields on some fixed-income instruments can decline.
However, existing investments and newly issued instruments can behave differently, depending on their structure and maturity.
For investors, the key issue will be how quickly the broader market adjusts to the CBN’s new policy direction.
4. Could businesses benefit from the CBN rate cut?
Businesses are among the groups that could benefit if lower policy rates eventually translate into cheaper credit.
For companies that depend on bank financing, lower borrowing costs could reduce financing expenses and make it easier to fund:
- Working capital
- Equipment purchases
- Expansion
- Inventory
- New projects
- Business restructuring
This could be particularly important for small and medium-sized enterprises that have struggled with high financing costs.
But the impact will depend heavily on how commercial banks respond.
5. Will Nigerians immediately see cheaper loans?
Probably not.
This is one of the most important points Nigerians should understand.
The CBN has changed the benchmark rate, but banks still determine the rates they charge individual customers.
A bank may take time to review its lending structure, funding costs and risk assessments before changing loan rates.
Some lending products may therefore become cheaper sooner than others.
Consumers should also check the effective interest rate, fees, insurance, processing charges and other costs attached to a loan rather than focusing only on the headline interest rate.
6. Will mortgage rates fall?
The CBN’s decision could eventually create room for lower mortgage financing costs, but there is no guarantee of an immediate reduction.
Mortgage rates depend on more than the MPR.
They can also reflect:
- Bank funding costs
- Loan duration
- Credit risk
- Property risk
- Capital requirements
- Inflation expectations
Therefore, Nigerians planning to take mortgages should watch how banks respond over the coming months rather than assuming the new MPR automatically means cheaper housing finance.
7. What does this mean for the naira?
Interest rates can influence foreign investment flows and demand for naira-denominated assets.
A lower rate can make some Nigerian fixed-income assets less attractive to investors seeking high yields.
At the same time, the CBN’s decision reflects its assessment of domestic economic conditions, including inflation and financial stability.
The impact on the naira will therefore depend on several factors, including foreign-exchange liquidity, oil prices, capital flows, inflation expectations and investor confidence.
It would be premature to assume that the rate cut alone will cause the naira to appreciate or depreciate by a particular amount.
8. Is the rate cut good news for the Nigerian economy?
The decision has potential benefits and risks.
Lower borrowing costs can support investment, consumer spending and business expansion.
However, monetary easing also needs to be managed carefully because a rapid increase in demand or liquidity could create renewed inflationary pressure.
That balance is particularly important because Nigerians are still dealing with elevated food prices and other cost-of-living pressures.
The latest NBS figures show that while headline inflation has moderated, food inflation remained significantly higher at 19.57 per cent in August.
There are also renewed pressures from higher petrol prices and global oil-market volatility. Reuters recently reported petrol prices around ₦1,400 per litre in Lagos and Abuja and up to ₦1,500 in parts of northern Nigeria.
That means the CBN still faces the challenge of supporting growth without allowing inflationary pressures to return.
9. What should Nigerians watch next?
The most important question after the MPC decision is now transmission.
In simple terms:
Will the rate cut actually reach the pockets of Nigerians?
Over the coming weeks, consumers and businesses should watch:
Bank lending rates
Will commercial banks reduce the cost of new loans?
Savings rates
Will banks reduce the interest paid on deposits and savings products?
Treasury bill yields
Will fixed-income yields adjust lower?
Mortgage rates
Will housing finance become cheaper?
Business credit
Will SMEs gain easier access to affordable financing?
Inflation
Will lower interest rates support growth without reigniting price pressures?
Naira stability
How will financial markets respond to the change in monetary policy?
CBN Rate Cut: The Bottom Line
The CBN’s decision to reduce the Monetary Policy Rate from 26.5 per cent to 23 per cent is a major change in Nigeria’s monetary policy direction.
It could eventually make borrowing cheaper and provide relief for businesses and consumers struggling with high financing costs.
But Nigerians should not expect their bank loans or mortgage payments to fall automatically tomorrow.
Similarly, savers should watch deposit rates because lower market rates could eventually reduce returns on some savings and fixed-income products.
The real test of the CBN’s decision will be whether the reduction in the policy rate translates into cheaper credit, stronger business activity and broader economic growth without triggering another wave of inflation.
For Nigerians, the next few weeks will show whether the 23 per cent rate becomes more than just a figure announced at an MPC briefing.
Quick Facts: CBN Interest Rate Cut
New MPR: 23%
Previous MPR: 26.5%
Reduction: 350 basis points
MPC meeting: 307th
CBN Governor: Olayemi Cardoso
August 2026 inflation: 15.39%
August food inflation: 19.57%
Standing Facilities Corridor: +50/-300 basis points around MPR
Next question: How quickly will banks transmit the rate cut?